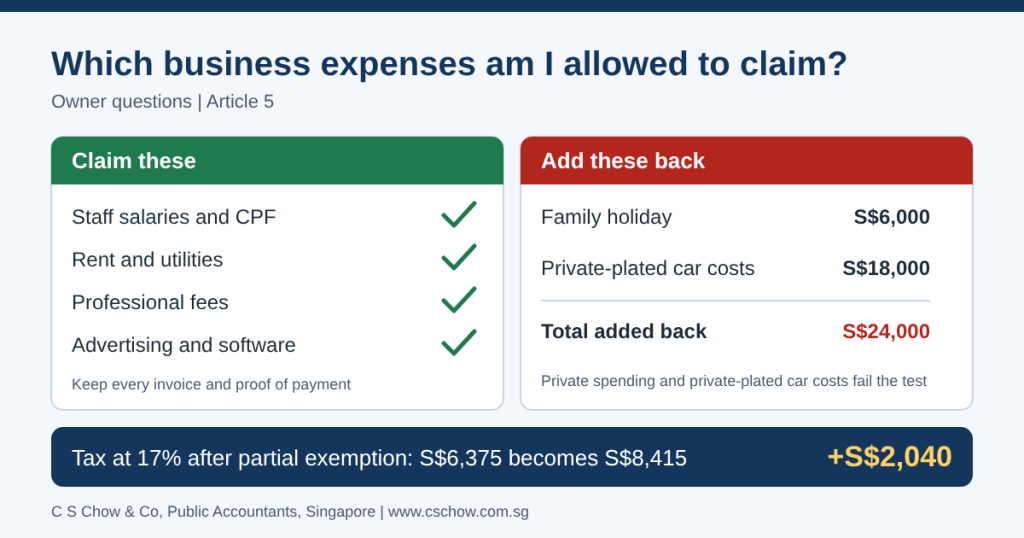
Your director paid S$24,000 last year for a family holiday and the running costs of a private-plated car. Your bookkeeper filed both under business expenses. IRAS rejects both. On the example below, your tax bill rises by S$2,040, and the same error repeats every year until someone corrects the books.
The test IRAS applies
IRAS allows a deduction when an expense meets four conditions:
- You incurred the expense wholly and exclusively to produce income.
- The expense is revenue in nature, like rent, salaries or software subscriptions.
- You paid or owe the amount. An estimate or contingent liability does not qualify.
- The Income Tax Act does not prohibit the deduction.
Staff salaries, CPF contributions, rent, utilities, professional fees, advertising and repairs usually pass. Keep the invoice and the proof of payment for each one.
What IRAS rejects
Capital spending fails the second condition. A new laptop, a machine or the cost of incorporating your company belongs here. You claim capital allowances on qualifying assets instead, and those follow separate rules.
Private spending fails the first condition. A director’s holiday, family dinners and personal shopping all fall in this group.
Private-plated car expenses face a direct prohibition. You lose the deduction even when you use the car for business.
Worked example
Your company reports an accounting profit of S$80,000. Inside the expenses sit S$18,000 of private-plated car costs and S$6,000 of holiday costs. You add back S$18,000 + S$6,000 = S$24,000.
Before the add-back, your chargeable income is S$80,000.
- Partial tax exemption: 75% x S$10,000 = S$7,500, plus 50% x S$70,000 = S$35,000. Exempt amount: S$42,500.
- Taxable income: S$80,000 – S$42,500 = S$37,500.
- Tax at 17%: S$6,375.
After the add-back, your chargeable income is S$104,000.
- Partial tax exemption: S$7,500, plus 50% x S$94,000 = S$47,000. Exempt amount: S$54,500.
- Taxable income: S$104,000 – S$54,500 = S$49,500.
- Tax at 17%: S$8,415.
The wrong claims would have saved you S$8,415 – S$6,375 = S$2,040. This example assumes your company does not qualify for the start-up exemption and ignores other adjustments.
Three habits protect your claims
- Pay private costs from your own pocket, or book them to your director’s loan account.
- Store every invoice and proof of payment on the day you receive them.
- Ask your accountant before you claim anything unusual, such as entertainment, home office or penalties.
Our corporate tax team prepares your tax computation and checks each expense before filing: https://www.cschow.com.sg/corporate-tax-singapore/
Send a WhatsApp message to +65 9876 3553 or email henry@cschow.com.sg. Tell me your year end and the three largest expense lines. I will tell you which ones need a closer look.
Henry Chow, Public Accountant, C S Chow & Co